Key Takeaways
- Protect people first, then prevent additional damage when it is safe to do so.
- Photographs, videos, receipts, and notes create a stronger record of the loss.
- Temporary stabilization can be necessary, but permanent repairs should follow inspections and a clear scope.
- Seattle-area rain, wind, fallen trees, plumbing failures, and fire damage can each create different restoration needs.
- Comparing detailed estimates helps property owners evaluate the work, not simply the lowest price.
Table of Contents
- What to do in the first few hours
- How to check whether the property is safe
- How to document the damage
- How to start the insurance process
- When temporary repairs make sense
- How response steps change by damage type
- How to build a clear repair scope
- How to review contractors and estimates
- Commercial property recovery priorities
- Common mistakes to avoid
- Final Thoughts
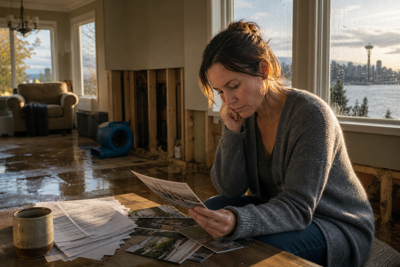
Major property damage can turn an ordinary day into a series of urgent decisions. Whether a Seattle home, rental property, storefront, or office has been affected by a burst pipe, wind-driven rain, fire, or a fallen tree, working with a qualified restoration company can help bring order to the first stages of recovery.
Seattle's wet seasons and tree-lined neighborhoods can make water intrusion and exterior damage especially stressful. A calm, documented process helps owners protect the property, communicate with insurers, and move toward repairs without overlooking safety concerns or important details.
What to Do in the First Few Hours
Start with the immediate risks rather than the cleanup. If there is fire, a gas odor, damaged electrical equipment, standing water near outlets, or signs of structural movement, leave the building and contact emergency services or the appropriate utility provider. Do not enter restricted areas simply to retrieve belongings.
- Confirm that occupants, pets, visitors, and nearby neighbors are safe.
- Shut off water, gas, or electricity only if it can be done safely.
- Keep people away from unstable ceilings, wet floors, broken glass, and damaged trees.
- Begin a written timeline of calls, site visits, expenses, and decisions.
- Notify the insurer or insurance agent promptly.
How to Check Whether the Property Is Safe
Visible damage does not always show the full extent of a loss. Water can travel behind walls and beneath flooring, while smoke residue can affect rooms beyond the area reached by flames. Have qualified professionals assess serious electrical, gas, structural, sewage, and hazardous-material concerns before reoccupying or beginning major cleanup.
Questions to Ask Before Re-Entering
- Are the roof, ceilings, floors, stairs, and exterior walls stable?
- Did water reach outlets, appliances, or the electrical panel?
- Is there a smell of gas, smoke, sewage, or a strong chemical odor?
- Are materials still wet enough to require drying or removal?
- Does the building need an inspection or permit before repairs begin?
How to Document the Damage
Document the property before materials are removed whenever conditions allow. Take wide photos of every affected room, then capture closer images of ceilings, walls, flooring, cabinets, fixtures, appliances, and damaged belongings. A narrated video walkthrough can also show how the damage relates from one area to another.
- Create an inventory with item descriptions, approximate age, and estimated replacement cost.
- Save receipts for lodging, meals, storage, emergency supplies, and temporary repairs.
- Keep inspection reports, estimates, invoices, permits, and claim correspondence in one folder.
- Record the date, time, and purpose of conversations with insurers, contractors, tenants, and lenders.
How to Start the Insurance Process
Policies, deductibles, deadlines, and coverage limits vary, so ask the insurer what documents are needed and whether an adjuster should inspect before permanent work begins. The steps for settling an insurance claim after a disaster emphasize documenting damage, keeping receipts, and obtaining detailed written repair bids.

Questions to Ask the Insurer
- What damage may be covered under this policy?
- What deductible and claim deadlines apply?
- Are emergency mitigation or temporary living expenses included?
- Will an adjuster inspect the property before permanent repairs?
- How should supplemental damage be submitted if new issues are found?
When Temporary Repairs Make Sense
Temporary work is intended to reduce further loss, not replace a complete repair plan. Boarding a broken window, placing a roof covering, extracting standing water, or securing a damaged entry may be appropriate. Photograph conditions first, retain receipts, and avoid discarding damaged items until they are documented or inspected unless they present an immediate health or safety concern.
How Response Steps Change by Damage Type
Water and Flood Damage
Water losses often require extraction, drying, moisture checks, and evaluation of drywall, insulation, flooring, cabinets, and contents. Hidden moisture can remain behind finished surfaces, so a repair plan should address both visible damage and affected materials that cannot dry properly.
Fire and Smoke Damage
Fire recovery may involve soot removal, odor control, contents cleaning, HVAC evaluation, electrical inspection, and repairs to heat-damaged building materials. Areas without visible flame damage can still require cleaning when smoke has traveled through the structure.
Storm, Wind, and Tree Damage
Seattle windstorms can leave roof openings, damaged siding, broken windows, clogged gutters, or water intrusion after branches fall. After emergency protection is in place, inspect for secondary water damage around attics, exterior walls, and window openings.
Sewage or Contaminated Water
Contaminated water requires special caution. Avoid direct contact, limit access to affected spaces, and use trained professionals when materials need sanitation, removal, or disposal.
How to Build a Clear Repair Scope
A detailed scope converts a confusing loss into measurable tasks. It should distinguish emergency stabilization from demolition, cleaning, drying, inspections, rebuilding, finish work, permits, and final cleanup. This clarity helps prevent missed work and makes estimates easier to compare.
- Site protection and emergency stabilization.
- Removal of damaged materials and debris.
- Drying, cleaning, deodorizing, or sanitation.
- Structural, electrical, plumbing, or HVAC inspections.
- Repairs to framing, roofing, drywall, flooring, cabinets, siding, and finishes.
- Permit coordination, required inspections, and closeout documents.
How to Review Contractors and Estimates
Review estimates based on scope, materials, scheduling, and accountability rather than price alone. Ask whether the contractor is properly licensed and insured for the work, who manages permits, how change orders are approved, and what payment schedule is proposed. Written estimates should clearly describe labor, materials, quantities, allowances, and exclusions.
Commercial Property Recovery Priorities
Commercial losses may involve employees, tenants, customers, vendors, equipment, records, lenders, and lost operating time. Establish one communication point of contact, secure records and critical equipment where possible, and prioritize repairs that restore safe building access and essential business functions. The financial steps after a disaster also include contacting lenders and utility providers early when damage affects normal operations or payment obligations.
Common Recovery Mistakes to Avoid
- Entering an unsafe building too soon.
- Starting permanent repairs before documenting the loss.
- Discarding damaged belongings without photographs or an inventory.
- Accepting an estimate without checking what work is excluded.
- Paying a large upfront amount without a written agreement.
- Ignoring minor moisture, odor, or structural concerns after emergency work.
- Failing to retain receipts, reports, and written communications.
Property recovery in Seattle becomes more manageable when decisions follow a clear order: protect people, limit additional damage, document the condition, understand the claim, and plan repairs carefully. That process cannot remove every challenge, but it can help owners make informed choices and move toward a safe, complete restoration.

(0) comments
We welcome your comments
Log In
Post a comment as Guest
Keep it Clean. Please avoid obscene, vulgar, lewd, racist or sexually-oriented language.
PLEASE TURN OFF YOUR CAPS LOCK.
Don't Threaten. Threats of harming another person will not be tolerated.
Be Truthful. Don't knowingly lie about anyone or anything.
Be Nice. No racism, sexism or any sort of -ism that is degrading to another person.
Be Proactive. Use the 'Report' link on each comment to let us know of abusive posts.
Share with Us. We'd love to hear eyewitness accounts, the history behind an article.